Golden Visa with a mortgaged property: what you need to know
8 min read 10
You can use a mortgaged property for a UAE Golden Visa if your DLD-registered share meets the minimum and your mortgage is current.
Quick answer
You can get a UAE Golden Visa with a mortgaged property. What matters is that you’re named on the title deed, your DLD-registered share meets the minimum, and your mortgage payments are up to date. As of November 2026, the key document is a recent mortgage statement from your bank that matches the deed. Always check the latest DLD valuation and the details on your statement before you apply.
You can get a Golden Visa with a mortgaged property
You don't need to pay off your loan first. For the UAE property investment Golden Visa, the Dubai Land Department only checks that your name is on the title deed, and that your share counts for enough. Most people applying in Dubai still have a mortgage. DLD rules expect it.
The minimum DLD-registered share for the 10-year Golden Visa is 2 million. If you and your spouse co-own an 4 million property with a 50/50 deed split, you're both eligible. But if three people split that 4 million, no one qualifies. The number is absolute here. No exceptions for close calls.
How mortgaged ownership is treated under DLD rules
You don't have to wait until the loan is gone. As long as your name is on the final title deed (not an off-plan or Oqood), you can use the property for your visa. Off-plan units and hotel apartments can't be used until after handover, when DLD lists you as an owner. That last step trips up more applicants than you'd think.
How your share is calculated with joint owners
DLD only goes by the title deed split. If the deed says you own a certain percentage, that's the share DLD uses. Doesn't matter who's been paying the mortgage. Before you file a Golden Visa application, check that the deed matches the mortgage agreement names and shares. If these don't match, you'll be stuck in the DLD portal for weeks, waiting for corrections.
DLD valuation: the number that counts
Only the DLD's valuation certificate matters for Golden Visa approval. What you paid, or what your agent says, doesn't come into it. You need a DLD valuation certificate (valid for 90 days) as part of every application, as of November 2026. That certificate decides if your property share meets the 2 million rule.

What if the DLD says your property is worth less?
If the DLD valuation is below what you paid, you’re stuck with that lower number. No negotiation. Some people see the DLD's value rise after a new assessment, but don't gamble on it. If you're not sure, we can arrange the DLD valuation before you pay application fees. Remember, those certificates only last for 90 days.
Property value dropping: do you lose the visa?
If the DLD valuation falls under 2 million for your share, you’re out. They check this again at renewal. So if the market shifts or DLD resets their calculation method, you could drop below the line. Many owners find out only at renewal, when there’s no workaround left.
How much equity is required?
You don't have to pay off the loan. DLD and immigration only check your DLD-registered property share, not your mortgage balance. Your name on the deed, share above 2 million, payments current — that's enough.
What documents do you need for a mortgaged property Golden Visa?
Here’s the short list: original or DLD-certified title deed, valid DLD valuation certificate (expires in 90 days), a mortgage statement from your bank dated within the last 30 days, a clear copy of your passport (all pages with UAE stamps), and your Emirates ID if you have one. Add a white-background passport photo and valid UAE health insurance. For family, bring attested marriage or birth certificates.
Banks used to demand a NOC. Now, only the mortgage statement matters. That statement must show your payments are current and that your name and property info match the title deed. If there’s a mismatch, tell the bank to fix it before you apply. We've seen many client delays come down to errors or inconsistencies here.
No more bank NOC needed in Dubai
The old process and what's changed
Before November 2026, every mortgaged property Golden Visa meant waiting for a bank NOC. Some banks charged for it, and the process dragged on. Now, DLD and GDRFA only want your latest mortgage statement. That's true for both new visas and renewals. You won’t have to chase your bank for a NOC anymore. See Bank NOC no longer required for any Dubai property visa — from our desk for the change straight from the specialists.
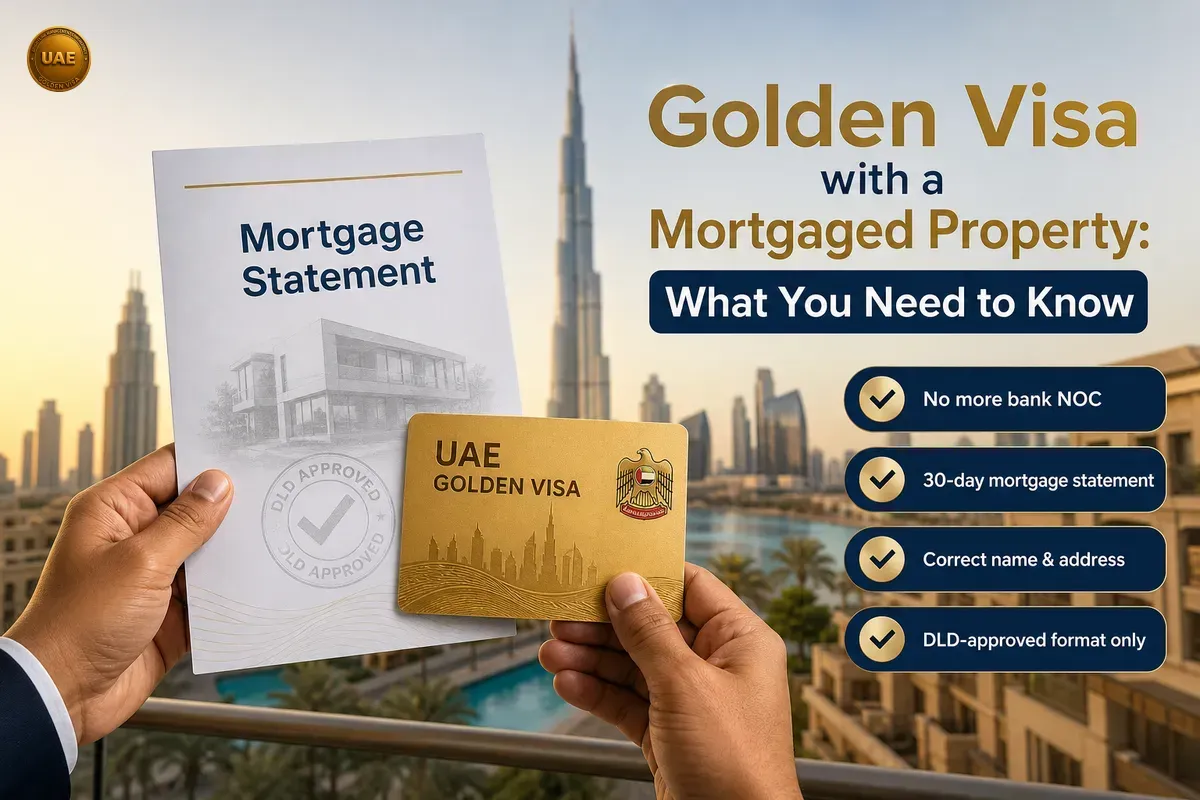
Ask your bank for a mortgage statement (sometimes called a liability letter or loan position letter) dated within the last 30 days. That statement must list your name and the property address exactly as on the DLD deed. If your bank gives you a blank template or generic letter, request the DLD-approved format. Some banks insist you pick it up in person, others email it to you. Don’t leave with the wrong document.
Refinancing, selling, or transferring a mortgaged property
Refinancing: will it affect your Golden Visa?
If you refinance, restructure, or switch banks, your eligibility stays if your name and share (2 million plus) remain unchanged on the deed. If you add or remove a co-owner, you need a new title deed and fresh mortgage statement before you renew. People often forget this step when updating ownership, then get caught out at renewal.
Selling: does the Golden Visa get cancelled?
Once you sell, your Golden Visa will be cancelled soon after DLD and GDRFA get the update. You pay a cancellation fee. To avoid gaps, line up your next eligible property or another visa, like an employment visa, before you sell. GDRFA takes this seriously.
Transferring or changing co-owners
Adding a spouse or removing a name from the deed counts as a new application for DLD and GDRFA. You'll need the updated deed and a recent mortgage statement. If your new share drops below 2 million, your eligibility disappears. Always check the numbers with DLD or your bank before signing anything at the trustee office.
Questions we get about mortgaged property and the Golden Visa
Does the amount I still owe matter?
No, it doesn’t. You can have most of your property financed. Only the DLD valuation and your share on the title deed count. Just keep your payments up to date.
Can you get a mortgage above property value?
No UAE bank will lend above DLD value. If your loan-to-value seems off, expect DLD to review your file in more detail.
Who can mortgage the property?
Only people on the DLD title deed can mortgage. For joint ownership, most banks want all owners to sign. Names must match exactly on the deed and bank statement. International spellings often cause headaches here.
How much does a Dubai mortgage cost?
Banks usually charge about 1 percent of the loan as a fee, and DLD charges 0.25 percent to register the mortgage. Check with your bank for other admin costs before you sign.
Can you get a mortgage against a property you own?
If you own a property outright, most banks offer you a loan against it. Watch that taking a new loan doesn't put your share below 2 million by DLD valuation, or you’ll lose eligibility for the Golden Visa.
The real issues that block or delay mortgaged Golden Visa cases
Title deed and mortgage statement don’t match
If the names, passport numbers or property details differ, your file will sit in limbo. The most common mistake is a spelling error or address that doesn’t match between your mortgage statement and the DLD deed. GDRFA or DLD will reject your case until it’s fixed. Ask the bank to update their files if needed. Don’t apply until you’ve checked every line.
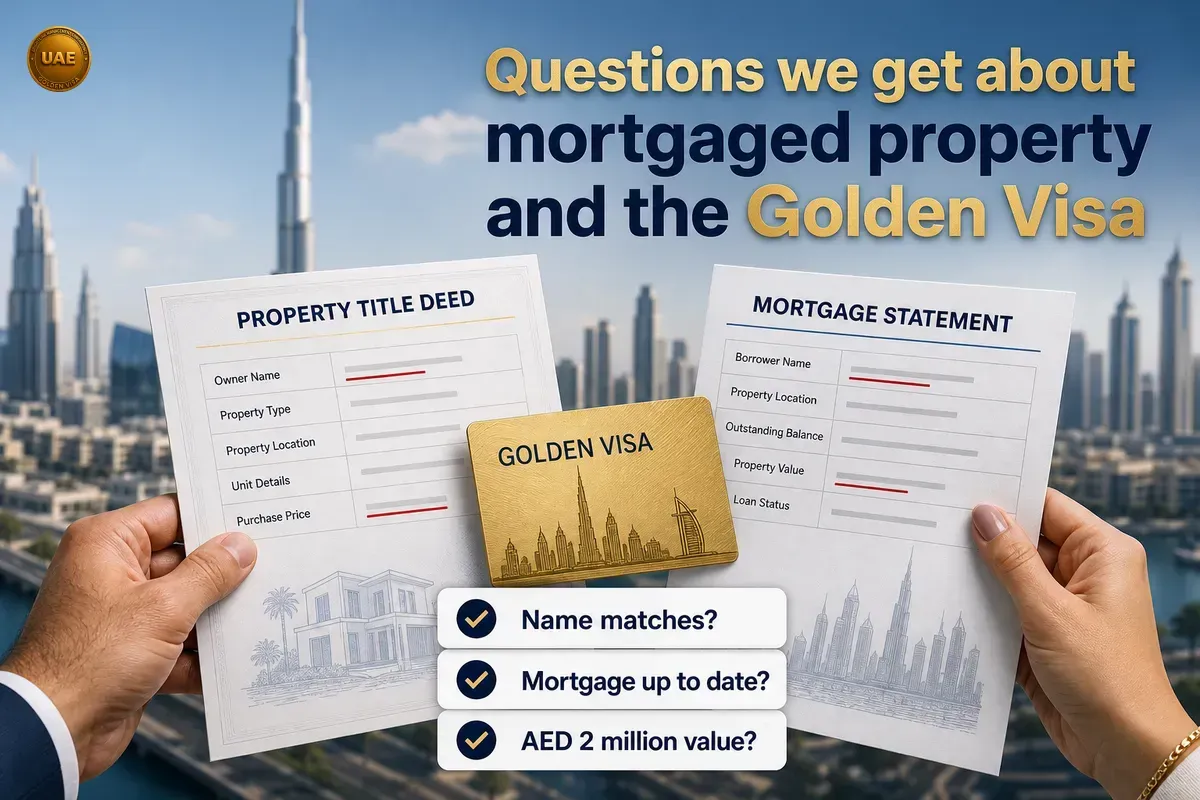
Missed mortgage payments
Late payments cause trouble. The bank may flag your mortgage, and DLD can freeze your visa process until you’re up to date again. Don’t try to apply if you’re overdue — it just wastes time.
Property value under the minimum
If the DLD valuation drops below 2 million for your share, you won’t qualify, even if last year you did. Get a current DLD valuation every time you apply or renew. Property values move, and so do DLD rules. To check the latest, see UAE Golden Visa Property Requirements: 2026 Valuation, Mortgages, and Fees.
Checklist: mortgaged property Golden Visa application
| Step | Document | Tip |
|---|---|---|
| 1 | Title deed (DLD) | Check your share and names |
| 2 | DLD valuation certificate | Must be 2 million or more for your share |
| 3 | Mortgage statement (last 30 days) | No missed payments, all names and details match title deed |
| 4 | Passport copy | Clear, valid, all pages with UAE visas |
| 5 | Emirates ID | Old or cancelled ID if renewing |
| 6 | Passport photo | Recent, white background |
| 7 | Health insurance certificate | UAE provider, valid for visa period |
| 8 | Marriage/birth certificates (for dependants) | Attested if issued outside UAE |
Before you apply, check every document for matching names, addresses, and numbers. Rules and forms change — review the latest DLD and GDRFA requirements or have us look through your file. If you’d rather not deal with the paperwork, talk to a consultant. We'll go over your title deed and mortgage statement line by line, then walk you through every next step.
For more, see our Dubai Golden Visa for property owners: the 2026 complete guide or try our Golden Visa cost calculator to estimate your fees and charges.
Frequently asked questions
Can I sell a mortgaged property if I have a Golden Visa?
Yes, but you’ll need to notify DLD and GDRFA. Your Golden Visa is cancelled after you no longer own the qualifying property. If you want continuous residency, arrange your new property or visa before you sell.
Can a mortgaged property be transferred to another person?
Yes. The new owner must qualify with both the bank and DLD. If your share falls below the Golden Visa minimum, the visa will be cancelled. Any ownership change needs updated immigration documents.
How is my share of a joint mortgaged property counted for the visa?
Your share is exactly what’s on the DLD title deed. DLD splits the valuation along these lines. If your deed shows 50% of a property valued at 4 million, you’re eligible—your share is 2 million.
Does the amount I still owe on the mortgage affect my eligibility?
No. You can qualify even if most of the property is financed. What matters is that your share by DLD valuation meets the minimum, and your mortgage is current.
What documents do I need from my bank for the application?
A recent mortgage statement (issued within 30 days). Dubai property Golden Visas haven’t needed a bank NOC since November 2026.
What happens if I miss a mortgage payment while holding the Golden Visa?
Missed payments will likely trigger a DLD block or bank flag, stalling your application or renewal. Get current before you apply.
Keep reading
Dubai Golden Visa Stay Requirements 2026: Eligibility, Documents, and Common Mistakes Explained
As of November 2026, Dubai Golden Visa holders can stay outside the UAE for over 6 months without losing their residency. Learn eligibility rules, required documents, photo specs, and how to avoid the mistakes that get files stuck.
· 10 min read
Dubai Golden Visa for Teachers: 2026 Eligibility, Step-by-Step Requirements, and Common Pitfalls
Teachers and education staff can now get Dubai’s 10-year Golden Visa. See if you qualify, what documents you'll need, fees, and tips to avoid file delays.
· 11 min read1
UAE Golden Visa: Long-Term Residency, Not Permanent Status
The UAE Golden Visa is a renewable 10-year residency—never permanent. Here’s what you really get, plus where applications usually get stuck.
· 6 min read1